
Watch the video
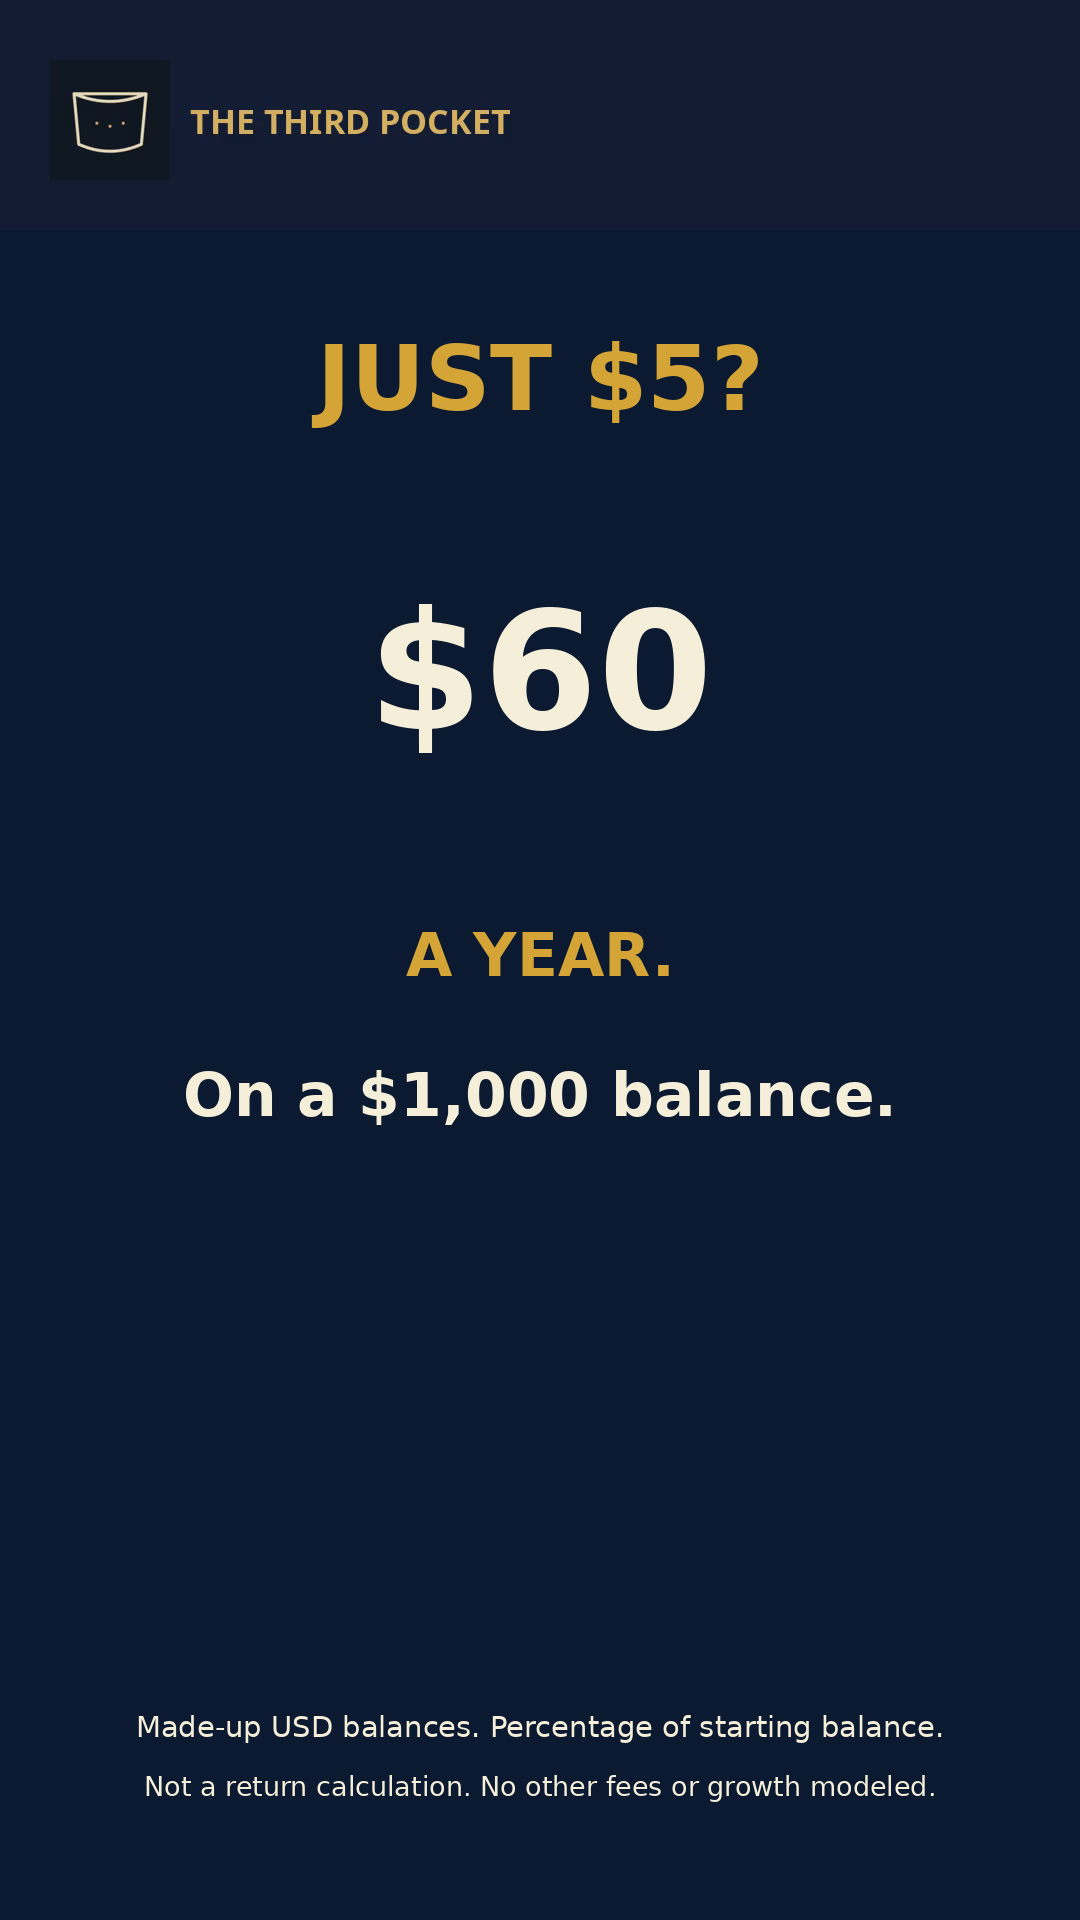
A $5 monthly fee is $60 a year.
On a made-up $1,000 starting balance, that is 6%. On $10,000, the same charge is 0.6%. The dollar fee did not change; the denominator did.
This is a fee-to-starting-balance comparison, not a return calculation. No growth, deposits, withdrawals or other fees are modeled.
Not investment advice.
Why a fixed fee hits small balances harder
A fixed charge does not shrink when the account balance is smaller. The example assumes twelve $5 charges, so the annual dollar charge is $60. Dividing that charge by each starting balance makes the comparison visible: 60 / 1,000 = 0.06; 60 / 10,000 = 0.006.
What the percentage does not mean
Six percent is not the account return or a forecast of performance. The balance could change as fees are deducted, and real accounts can have minimum-balance waivers or other terms. This deliberately holds the denominator at the starting balance. A percentage-based fund expense ratio works differently from a fixed account fee.
Explore further
Related tool models percentage fund fees, not this flat account charge. It does not calculate this flat-fee example.