
Watch the video
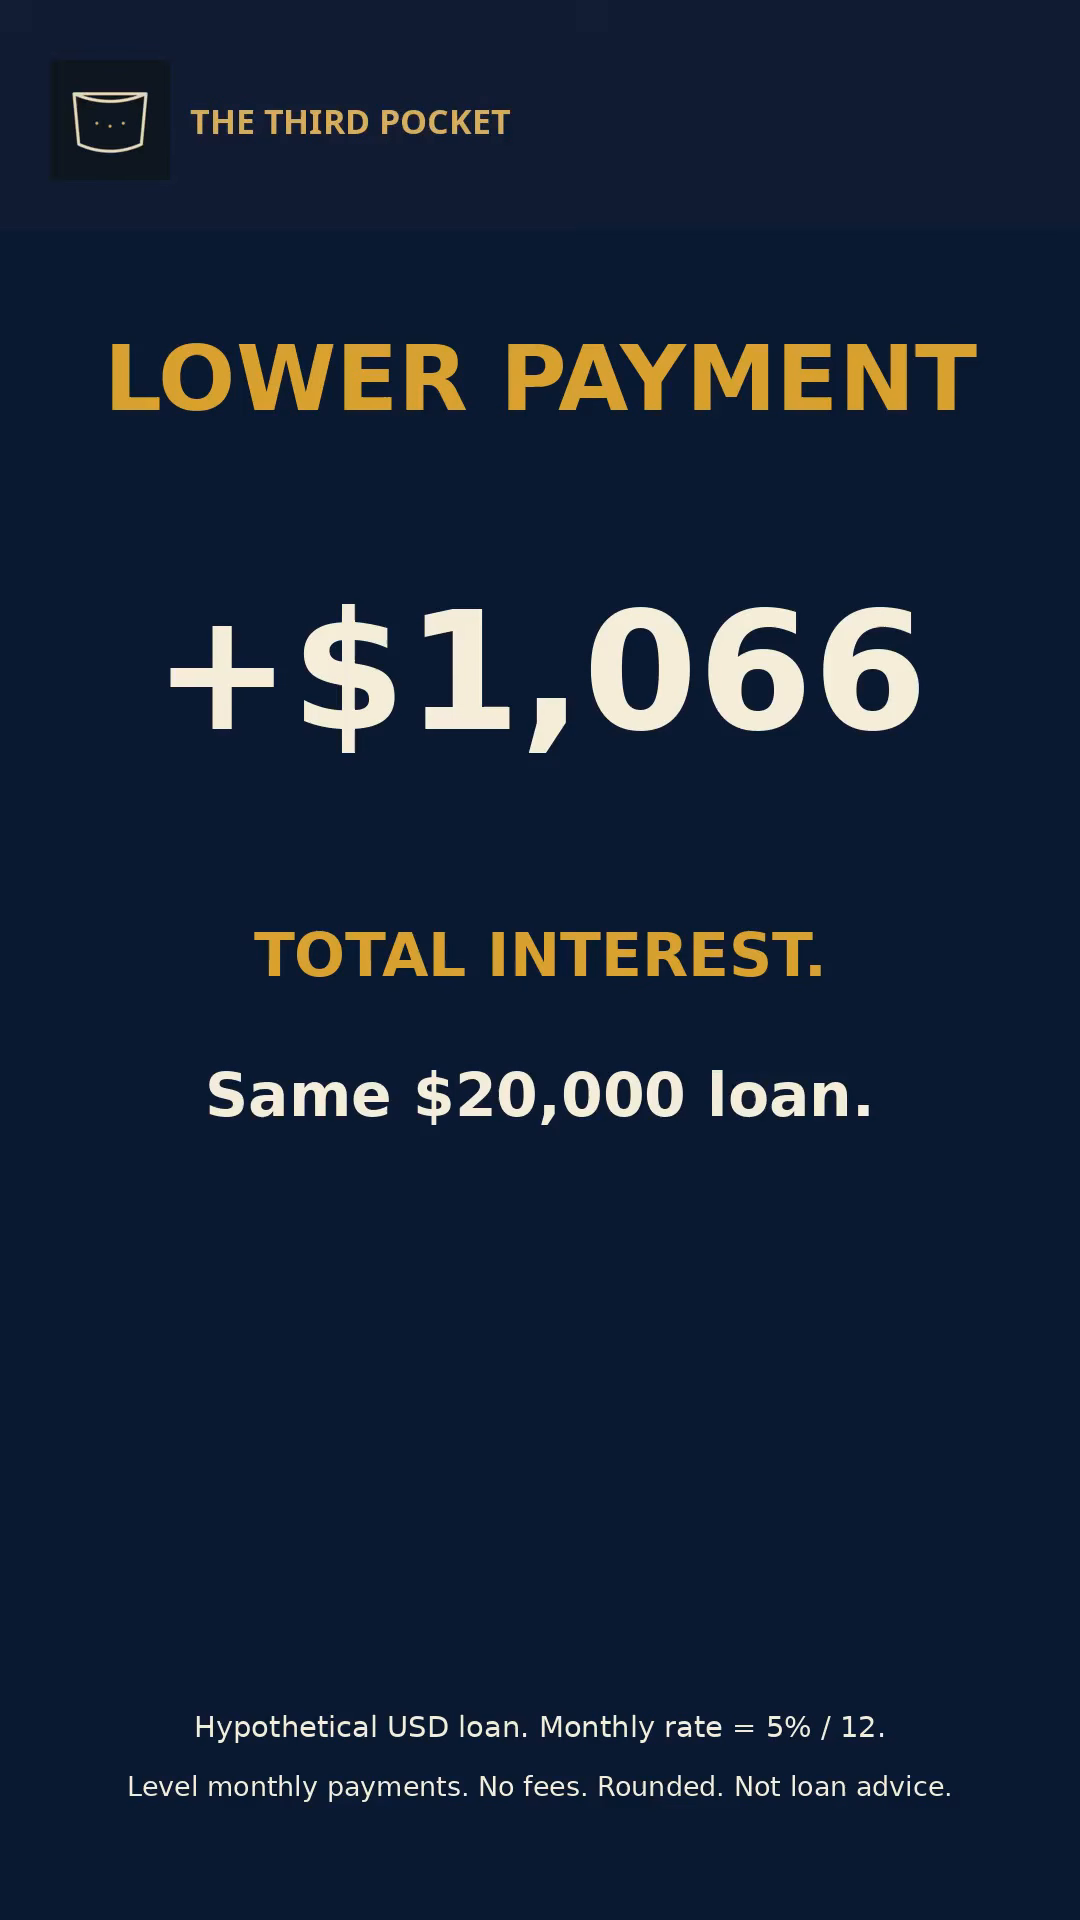
A smaller loan payment can carry a larger total interest bill.
Made-up $20,000 loan at a fixed 5% annual rate, with monthly payments: 36 months costs about $599 a month and $1,579 interest; 60 months costs about $377 a month and $2,645 interest. About $1,066 more interest.
Calculated with monthly rate 5% / 12 and unrounded payments; displayed figures are rounded. No fees. Not a loan offer.
Not borrowing advice.
Same rate, different repayment clock
For a level-payment loan, payment = P r / (1 - (1+r)^(-n)), where P is $20,000, r is 0.05/12, and n is the number of monthly payments. The 36-payment result is $599.417942; the 60-payment result is $377.424673. Total interest uses the unrounded payment multiplied by n, minus the original principal.
The trade-off behind the smaller bill
Total interest is $1,579.045915 for 36 months and $2,645.480373 for 60 months. The difference is $1,066.434457. A longer term lowers the payment but leaves debt outstanding for longer. These are made-up terms, not a lender quote. Actual fees, APR conventions, payment rounding and timing can change the bill.
Explore further
Explore how mortgage interest adds up over a loan term. The related calculator uses mortgage terms, not the generic loan terms in this example.